Travel Advice
Jersey Duty-Free Allowances and Customs Limits Explained
Updated 25 October 2026
If you are planning a trip across the English Channel to Jersey, you might naturally wonder how customs and border formalities work. The flight from the south coast takes under an hour, British currency is accepted everywhere, and there are no passport control gates upon arrival. Because Jersey sits so close to England and maintains deep constitutional ties to the British Crown, many travellers assume the island is treated just like mainland Britain.
However, when it comes to luggage, shopping, and duty-free goods, that assumption can quickly lead to an expensive surprise. Jersey is not part of the United Kingdom, nor is it part of the UK VAT territory or customs area. Crossing the sea between Jersey and Great Britain means crossing an international customs border. While this status unlocks genuine duty-free prices on spirits, wine, tobacco, and luxury items, strict statutory limits govern what you can bring back tax-free.
Whether you are holidaying in Jersey or returning to the UK, I have put together this guide to clarify the official allowances, monetary limits, and customs declaration rules.
Understanding Jersey's Customs and Border Status
To make sense of duty-free limits, it helps to understand how Jersey relates to the United Kingdom. Jersey is a self-governing British Crown Dependency with its own parliament, legal system, and tax authority. For immigration purposes, Jersey belongs to the Common Travel Area (CTA), which includes the UK, Guernsey, the Isle of Man, and Ireland.
Under CTA rules, there are no routine immigration border controls when travelling directly between Jersey and the UK. British and Irish citizens do not strictly need a passport to enter Jersey, though you must carry photographic identification, such as a driving licence or passport, to satisfy transport carriers and port authorities.
Customs controls, however, operate under separate legislation. While immigration is shared across the CTA, fiscal jurisdictions are distinct. Jersey operates its own customs agency, charging local Goods and Services Tax (GST) and island excise duties. Similarly, HM Revenue and Customs (HMRC) monitors arrivals into Great Britain. Because goods purchased in Jersey do not include UK duty or VAT, the UK enforces identical personal allowances on arrivals from Jersey as it does on travellers from non-EU countries.
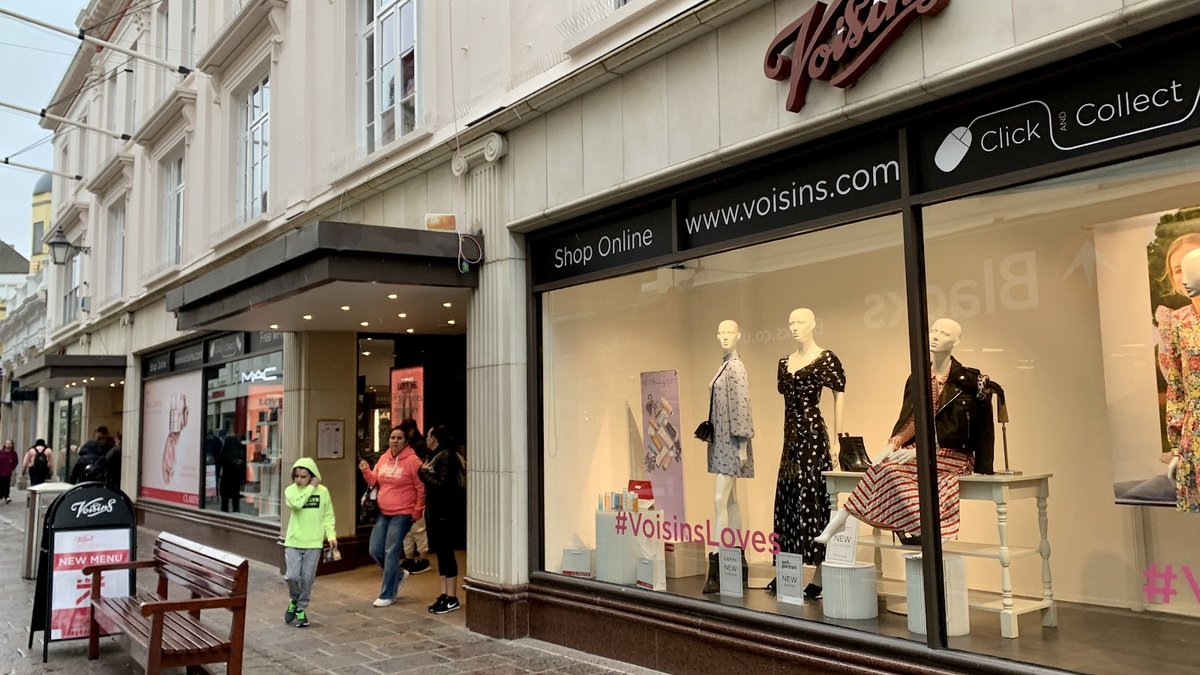
This dynamic makes Jersey an attractive shopping destination. In St Helier, visitors can browse historic establishments like Voisins Department Store on King Street, sampling designer brands, fragrances, and clothing alongside local goods. Wherever you shop, staying within statutory limits ensures your purchases remain duty-free.
Returning to Great Britain: Inbound UK Customs Allowances
When returning to Great Britain (England, Scotland, and Wales) from Jersey, your personal allowance lets you bring in a set quantity of goods without paying UK excise duty or VAT. These exemptions apply strictly to items intended for your personal use or as gifts. No personal allowances exist for commercial goods or items intended for resale.
UK customs groups allowances into three distinct categories: alcohol, tobacco, and other goods. Exceeding your limit in any single category triggers tax across that group.
Alcohol Allowances Entering the UK
The UK alcohol allowance allows you to bring in both beer and wine, alongside an allowance of spirits or fortified drinks:
- Beer and cider: Up to 42 litres.
- Wine: Up to 18 litres of still or sparkling wine (around 24 standard 75cl bottles).
- Spirits: Up to 4 litres of spirits or alcoholic beverages over 22% alcohol by volume (ABV), or
- Fortified wine and lighter liquors: Up to 9 litres of drinks up to 22% ABV (such as port, sherry, or sparkling wine, excluding beer, cider, and still wine).
You may split this final spirit and fortified wine allowance. For instance, you could carry 2 litres of spirits (50% of the spirits allowance) plus 4.5 litres of fortified wine (50% of the fortified allowance). You cannot, however, trade unused beer or wine quotas for additional spirits.
Tobacco Allowances Entering the UK
For tobacco products, you can bring in one of the following:
- 200 cigarettes, or
- 100 cigarillos, or
- 50 cigars, or
- 250 grams of tobacco, or
- 200 sticks of tobacco for electronic heated tobacco devices.
This allowance can also be split proportionally. For example, you can bring 100 cigarettes (half the limit) and 25 cigars (half the limit).
Vaping Liquid and Age Rules
Travellers entering Great Britain can import up to 50ml of vaping liquid within their personal allowance.
Crucially, travellers under the age of 17 have no personal allowance for alcohol, tobacco, or vaping products. Minors must declare any such items before arriving in the UK, and all items are liable for tax and excise duty.
General Goods, Gifts, and Souvenirs
For all other items—including perfume, electronics, souvenirs, and apparel—the UK applies a value threshold:
- Commercial travel (airline or ferry): Goods worth up to £390 per passenger.
- Private boat or plane: Goods worth up to £270 per passenger.
If any single item exceeds your allowance, you cannot claim duty-free status on any part of its value.
| Category | UK Allowance (Entering Great Britain) | Rules and Splitting |
|---|---|---|
| Beer and Cider | 42 litres | Separate from wine and spirits. |
| Wine | 18 litres | Still or sparkling wine. |
| Spirits (>22% ABV) | 4 litres | Can be split with fortified wine. |
| Fortified Wine (≤22% ABV) | 9 litres | Port, sherry, and lower-strength liqueurs. |
| Tobacco | 200 cigarettes OR 100 cigarillos OR 50 cigars OR 250g tobacco OR 200 heated sticks | Choose one or split proportionally. Under-17s have no allowance. |
| Vaping Liquid | 50ml | Under-17s have no allowance. |
| Other Goods | £390 commercial / £270 private transport | Covers electronics, perfumes, and clothing. |
Entering Jersey: Customs Allowances from the UK
Many visitors forget that customs boundaries operate in both directions. When travelling from the UK to Jersey, the States of Jersey applies its own personal import allowances. Travellers aged 17 or older can bring in goods free of customs duty and GST, provided they are for personal, non-commercial use.
Standard Personal Allowances
When entering Jersey, the standard personal allowance per passenger aged 17 or over permits:
- Spirits: 1 litre.
- Wine: 4 litres.
- Beer or cider: 16 litres.
- Tobacco: 200 cigarettes or 250 grams of other tobacco products.
- E-liquid: 50ml.
If you bring in goods exceeding these amounts, you must declare them. Failure to declare means you lose your entire duty-free allowance, and all excess alcohol, tobacco, or e-liquid will be confiscated.
The Jersey Alternative Allowance for Wine and Beer
If you prefer wine or beer over spirits and tobacco, Jersey provides a generous alternative allowance. If you choose not to import any spirits or tobacco products, you may select one of the following expanded quotas:
- Alternative Wine Allowance: 36 litres of wine (equal to 48 standard 75cl bottles), or
- Alternative Beer Allowance: 110 litres of beer.
This alternative concession is ideal for holidaymakers taking a car ferry to stock a self-catering stay. Remember, however, that selecting an alternative allowance requires giving up your spirits and tobacco limits completely; you cannot carry a single bottle of gin or pack of cigarettes alongside your 36 litres of wine.
General Goods and Gifts Entering Jersey
Jersey enforces a strict monetary cap on miscellaneous goods, gifts, and souvenirs:
- Commercial air or sea travel: Up to £390 of other goods.
- Private air or sea transport: Up to £270 of other goods.
These monetary thresholds apply to passengers of all ages, offering younger travellers an allowance for toys, tech, and clothing.
| Category | Jersey Standard Allowance | Jersey Alternative Allowance (No Spirits/Tobacco) |
|---|---|---|
| Spirits | 1 litre | Nil (must forfeit entirely) |
| Wine | 4 litres | 36 litres (48 standard 75cl bottles) |
| Beer / Cider | 16 litres | 110 litres of beer (or 16L cider) |
| Tobacco | 200 cigarettes OR 250g tobacco | Nil (must forfeit entirely) |
| E-Liquid | 50ml | 50ml |
| Other Goods | £390 commercial / £270 private | £390 commercial / £270 private |
Critical Customs Traps: Pooling and the All-or-Nothing Rule
Understanding the numbers is essential, but understanding how border authorities enforce them is equally critical. Two common pitfalls frequently surprise travellers: the rule against pooling allowances and the all-or-nothing penalty.
The Prohibition on Pooling Allowances
Customs allowances are strictly personal to each individual passenger. You cannot pool individual allowances together to cover a single item that exceeds the limit.
For example, if you and your travelling partner see a watch in Jersey priced at £600, you cannot combine your two £390 allowances (£780 total) to import it duty-free. Because the watch is a single, indivisible object, it belongs to one person. Since its value exceeds £390, that single item must be declared, and customs charges will apply.
The same restriction applies to alcohol and tobacco. Each traveller must independently transport and claim their own allocated share.
The All-or-Nothing Duty Penalty
A frequent misconception is that exceeding an allowance means paying tax only on the excess amount. For instance, if you bring 19 litres of wine into Great Britain against an 18-litre allowance, you might expect to pay duty on the one extra litre.
In practice, UK customs rules dictate that if you go over your allowance, you must pay tax and duty on all goods in that category. Bringing 19 litres of wine means you forfeit your allowance, becoming liable for excise duty and VAT on all 19 litres.
Similarly, for general goods entering the UK or Jersey, bringing an item valued at £450 on commercial transport does not mean paying tax on the £60 excess above £390. You must pay import VAT and duty on the entire £450 value. Exceeding your limit by even a modest margin can quickly erase any duty-free savings.
How and When to Declare Goods to UK Customs
If you exceed your personal allowances, or carry banned or restricted items, you must declare them before crossing the UK border. Failing to declare goods can lead to item confiscation, vehicle seizure, financial penalties, or prosecution.
Declaring Goods Online
The UK Government provides an online declaration service that allows you to declare goods before arrival. You can access this service from 5 days (120 hours) prior to your scheduled arrival in the UK.
Using the online system provides distinct benefits:
- Simplified rates: Customs and excise duties are calculated using standardized simplified rates.
- Pre-payment: You can pay tax and duty online before travelling using a debit or credit card.
- Direct border clearance: After declaring, you receive an email receipt and reference number. On arrival at a UK port or airport, you can proceed directly through the green "nothing to declare" channel. Border Force officers may ask to see your confirmation receipt during spot checks.
To use the online service, you need your travel details, passport or photo ID number, and receipts showing the exact prices paid in the original currency.
Declaring at the Border
If you cannot use the online portal, or if you acquire extra goods right before boarding, you must declare your items upon arrival. Look for the red customs channel or use the red-point phone in the arrivals hall before leaving baggage reclaim. Officers will check your goods and calculate the tax owed.
Practical Tips for a Smooth Journey
Keeping a few simple travel habits in mind ensures your crossing remains hassle-free:
- Keep your receipts: Always retain itemized receipts for your purchases. Without receipts, customs officials can assess an item's market value, which may be higher than what you actually paid.
- Mind airport liquid rules: If you buy alcohol in town before reaching Jersey Airport, remember that bottles over 100ml cannot go into cabin baggage. They must be safely packed in your checked hold luggage. If you travel with hand luggage only, purchase your drinks at the airport departure lounge after security.
- Consider ferry travel for volume: If you want to take full advantage of your liquid allowances—such as bringing 18 litres of wine back to the UK or taking 36 litres to Jersey under the alternative allowance—taking a vehicle ferry offers convenient luggage capacity without airline weight constraints.
- Pack allowances individually: Keep each traveller's purchases clearly separated within their own bags to avoid confusion during customs checks.
Understanding how customs rules work between Jersey and the UK allows you to enjoy duty-free shopping with total peace of mind, ensuring a seamless journey from island shores to your front door.
Cover photo: Voisins Department Store
By Alyssa.
Sources and further information
- Bringing goods into the UK for personal use: Overview - GOV.UK
- Bringing goods into the UK for personal use: Arriving in Great Britain - GOV.UK
- Bringing goods into the UK for personal use: When to declare goods to UK customs - GOV.UK
- Check what travel documents you need to enter Jersey
- Duty free allowances
- Bringing goods into the UK for personal use: Declare goods and pay tax and duty to UK customs - GOV.UK
Sources checked: 2026-10-25.